
First Home Buyers Loan Requirements: What You Need to Qualify

Qualifying for a first home loan comes down to five checks: ownership history, credit score, debt-to-income ratio, a documented down payment source, and proof you intend to occupy the home. Most lenders will not move past application without a specific stack of paperwork, and gathering it before you call anyone saves weeks.
Here’s the one-minute list to pull together first:
Photo ID and Social Security card or ITIN
Pay stubs covering the last 30 to 60 days
W-2s for the past two years
Signed federal tax returns for the past two years
Bank and investment statements for the last two months
Gift letter (signed, if any down payment funds come from family)
Most first-time buyer programs lean on HUD’s three-year rule: no ownership interest in a primary residence for three years before purchase. Exceptions exist for single parents and displaced homemakers, which we cover next.
Key Takeaways
Qualifying for a first home loan depends on clean ownership history, an acceptable credit and DTI profile, a documented down payment, and a complete paperwork stack ready before you apply.
Point | Details |
Confirm first-time status | Check HUD’s three-year ownership rule and ask about exceptions if you’ve owned property before. |
Gather core documents early | Pay stubs, two years of W-2s and tax returns, and two months of bank statements cover most lender requests. |
Match program to profile | FHA, VA, USDA, and conventional loans each fit different credit, income, and location situations. |
Fix credit and DTI before applying | Dispute errors and pay down balances 30 days to six months ahead of your application. |
Schedule an inspection early | Trinity Home Inspections’ same-day reports with free thermal imaging help you spot issues before they slow down underwriting. |
First Home Owner Loan Requirements: Who Counts as a First-Time Buyer
HUD’s baseline definition is straightforward: you qualify as a first-time homebuyer if you have not held ownership interest in a principal residence during the three years leading up to your purchase date, according to HUD’s archived first-time homebuyer guidance.
That baseline has real exceptions built in. Federal statute protects certain buyers from losing first-time status just because of past circumstances:
Single parents who owned a home only with a former spouse
Displaced homemakers with no ownership stake of their own
Buyers whose prior property was not habitable and could not be economically repaired
The look-back period is a federal standard used across most national programs, but state and local down payment assistance programs sometimes apply their own window, so always confirm before assuming you’re disqualified.
Mortgage Eligibility Criteria Lenders Check Before Approving You
Every lender runs the same core checks regardless of loan program, and understanding them helps you spot weak points before an underwriter does.
Ownership and occupancy. Lenders want to see you intend to occupy the property as your primary residence. Investment purchases and second homes carry different rules and often stricter down payment requirements.
Residency and citizenship. You’ll need a valid Social Security number or ITIN. Veterans and active service members qualify for VA loan benefits through a Certificate of Eligibility, which we’ll cover in the programs section below.
Income documentation. Lenders verify income through pay stubs, W-2s, and tax returns, per CFPB guidance on loan application packets. Programs with income caps (common in USDA and many local assistance programs) also require you to prove your household falls under the limit.
Asset verification. Every dollar toward your down payment gets traced. Bank statements, investment account statements, and signed gift letters (if family is contributing funds) all get reviewed.
Ownership history spanning the last three years
Occupancy intent for the property
Valid SSN or ITIN on file
Two months of asset statements matching your stated down payment
Pro Tip: If a family member is gifting part of your down payment, get the signed gift letter finalized before you submit your application. An unlabeled deposit into your account will look like undisclosed debt to an underwriter, and that can quietly wreck your debt-to-income ratio.
Common Loan Programs for First-Time Buyers
Four loan types dominate the first-time buyer market, and each one fits a different financial profile. Matching yourself to the right program before applying saves you from a denial that had nothing to do with your actual ability to pay a mortgage.
FHA loans work well for buyers with thinner credit files or smaller down payments. HUD’s buying-a-home hub highlights FHA as one of the most accessible entry points for first-time buyers, largely because of its lower down payment threshold.
VA loans serve veterans, active duty service members, and eligible surviving spouses. They typically require no down payment and no private mortgage insurance, though a funding fee applies in most cases.
USDA loans target buyers purchasing in eligible rural and some suburban areas, with income limits tied to the local area median.
Conventional mortgages demand stronger credit but offer more flexibility on property type and occupancy, plus better long-term pricing once you clear the higher credit bar.
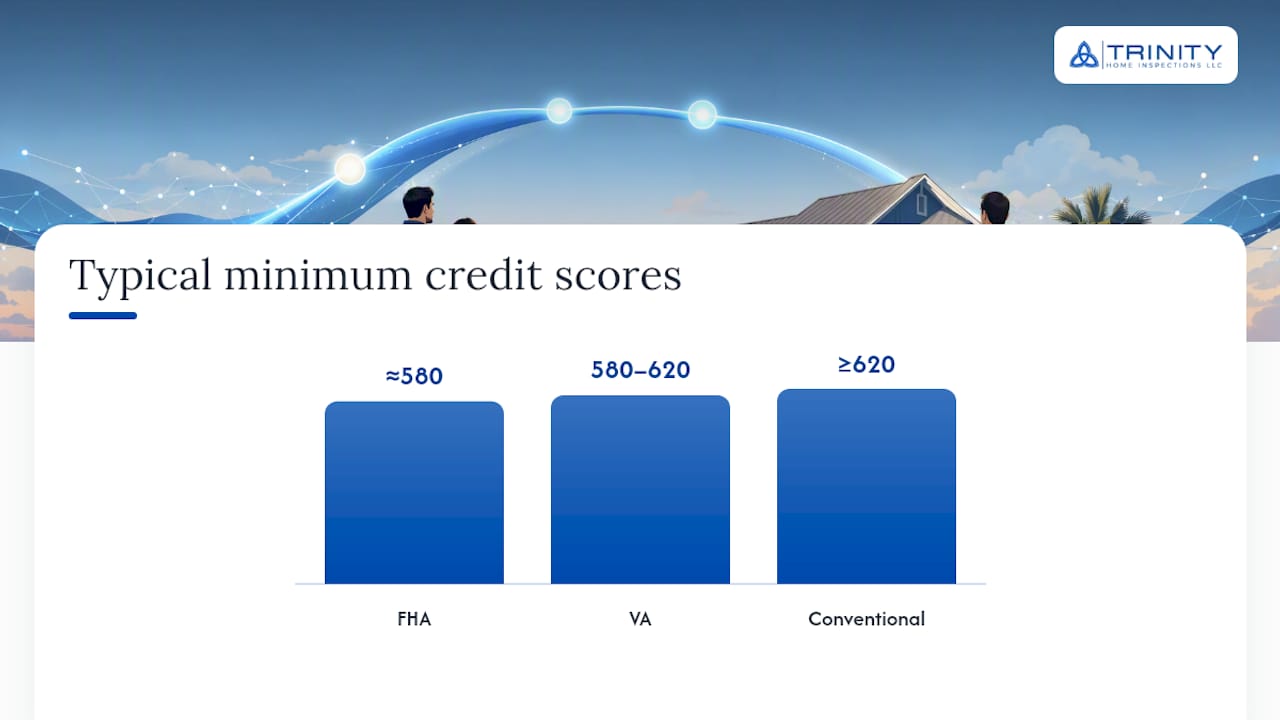
Program | Minimum credit score | Minimum down payment | Typical DTI limit | Best for | Program-specific requirements |
FHA | Around 580 for the lowest down payment tier | Lower down payment thresholds | Often up to 43-50% | Buyers with limited credit history or savings | Property must meet FHA condition standards |
VA | No official minimum, lender-set (often 580-620) | No down payment requirement in most cases | Flexible with compensating factors | Veterans and active service members | Certificate of Eligibility required |
USDA | Minimum credit scores vary by program | No down payment requirement | Around common maximums near 43% | Rural and some suburban buyers | Household income under area limits |
Conventional | Typically 620 and up | As low as 3% for qualified first-time buyers | Usually under common maximums around 43% | Buyers with stronger credit and stable income | No specific property or income limits |
A few tradeoffs worth weighing before you pick a lane:
FHA’s lower entry bar comes with mortgage insurance premiums that last the life of many loans.
VA loans skip the down payment but only apply if you have qualifying service history.
USDA loans require rural or eligible suburban geography, which rules out plenty of buyers by location alone.
Conventional loans reward higher credit scores with better rates, but the underwriting bar is less forgiving of thin credit files.
If you’re eyeing an FHA loan specifically, the property itself has to clear certain condition standards. Our breakdown of FHA home inspection requirements walks through what typically trips up older homes.
Documentation Checklist for a First Home Buyer Loan
Lenders work from a fairly consistent document list no matter which program you pursue. Gathering these before your first conversation with a loan officer speeds up preapproval considerably.
Photo ID and Social Security card or ITIN
Pay stubs covering the most recent 30 to 60 days, per CFPB’s loan application packet guidance
W-2s for the last two years
Signed federal tax returns for the last two years
Bank and investment statements for the last two months, showing every page
Gift letter, signed by the donor, if any funds are gifted rather than earned
Purchase agreement once you’re under contract, plus HOA documents if applicable
Self-employment documentation, including profit and loss statements and two years of business tax returns, for anyone who owns 25% or more of a business
Court orders for alimony or child support, if you’re counting that income or paying it out
Certificate of Eligibility, for veterans pursuing a VA loan
Fannie Mae’s mortgage documentation guide confirms this same core list, with added notes for self-employed applicants and digital verification options some lenders now accept in place of paper statements.
Pro Tip: Name every PDF clearly before you send it. “BankStatement_March_JohnSmith.pdf” beats “Scan001.pdf” every time, and it keeps your loan officer from bouncing your file back with a request you could have avoided.
How Underwriters Score Your Credit, Debt, and Reserves
Underwriting boils down to three numbers: your credit score, your debt-to-income ratio, and your reserves.
Credit score bands determine which programs you can access and what rate you’ll pay. Scores in the upper 700s open up the best conventional pricing. Scores in the 580 to 620 range still work for FHA and often VA, but with less favorable terms.
Debt-to-income ratio (DTI) measures your monthly debt payments against your gross monthly income. Lenders typically want to see this at or below a common threshold, though FHA and VA programs sometimes stretch that ceiling with strong compensating factors like large reserves or excellent credit history.
Recent collections or charge-offs will draw direct underwriter questions
Late payments in the past 12 months carry more weight than older ones
Large, unexplained deposits get flagged and require a paper trail
New credit accounts opened right before closing can delay or derail approval
A share of mortgage applicants face at least one denial before securing final approval, as reported by Zillow’s mortgage documentation research, and incomplete paperwork is one of the most common triggers.
Pro Tip: Avoid opening new credit cards, financing a car, or moving large sums between accounts in the 60 days before closing. Underwriters re-check credit right before funding, and a new inquiry can force a second review.
How to Improve Your Odds Before You Apply
A few targeted moves in the months before you apply can shift you into a stronger loan tier.
Pull your credit report and dispute errors. Correcting inaccurate items typically takes 30 to 45 days to reflect.
Pay down credit card balances. Lowering revolving debt improves your DTI within one to two billing cycles, though the full effect on your score often takes one to six months.
Document gift funds early. Get signed gift letters finalized well before you submit an application, not after a loan officer asks for one.
Build reserves. Two to six months of mortgage payments in savings strengthens your file, especially for self-employed applicants.
Talk to a HUD-approved housing counselor. HUD’s buying-a-home resources connect you with free or low-cost counseling to walk through your specific numbers.
For a broader roadmap covering the earlier planning stages, our first-time home buyer guide fills in the steps before you reach this checklist.
Finding State and Local First-Time Buyer Assistance
Down payment and closing cost assistance often comes from your state housing finance agency or a local nonprofit, not the federal government directly. Usa is a solid starting point for locating homeownership vouchers and other programs tied to your area.
Most local programs layer additional requirements on top of federal rules:
Household income caps, often tied to area median income
Occupancy or resale restrictions, sometimes lasting several years
Mandatory homebuyer education courses before closing
Property type limits, excluding investment or multi-unit purchases
Confirm every detail directly with the administering agency. Program rules shift year to year, and the documents they request can differ slightly from what your lender needs.
What to Expect from Preapproval to Closing
Preapproval usually takes a few days once your documents are in order. Underwriting stretches longer, often two to four weeks, and can stall if the underwriter requests additional paperwork mid-process. Appraisal scheduling adds another week or two, and closing typically follows 30 to 45 days after your purchase agreement is signed.
Budget for these upfront costs alongside your down payment:
Earnest money, often 1-3% of the purchase price, held in escrow
Home inspection fees, generally a few hundred dollars depending on property size
Appraisal fees, usually paid at application or rolled into closing costs
Closing costs overall, commonly ranging from 2% to 5% of the loan amount
Rate locks typically happen once you’re under contract and moving through underwriting, not before. Locking too early risks expiration before closing; locking too late exposes you to rate movement.
Why a Home Inspection Matters for Loan Approval
Underwriters and appraisers care about property condition, and a thorough inspection often surfaces issues before they become closing-day surprises. Inspectors check structural integrity, electrical panels, plumbing, roofing, and HVAC systems, flagging anything that could affect the appraisal or trigger a lender’s repair requirement, especially on FHA-backed purchases.
Trinity Home Inspections’ reports break findings into three clear categories: DIY/Minor, Issues/Defects, and Safety/Major, so you know exactly what needs attention before closing and what can wait.
Full structural, electrical, plumbing, and HVAC review
Free thermal imaging to spot hidden moisture or insulation gaps
Same-day digital reports with photos and video
Add-on services like sewer scope, mold testing, and air quality sampling
Pro Tip: If you’re buying under an FHA loan, ask your inspector about property condition standards before you’re deep in underwriting. Our guide on inspection steps for first-time buyers covers exactly what those standards look for.
A Few Honest Words on What Slows Buyers Down
The buyers who hit the fewest delays are the ones who over-communicate early: they tell their lender about a late payment before it shows up in underwriting, and they hand inspectors every access point without hesitation. The ones who stall usually hid something small, hoping it wouldn’t matter. It always matters. Keep duplicate copies of every document you send, and loop your lender and inspector in on anything unusual about your credit or the property before either one finds it first.
Ready to Move Forward With Confidence?
A clean inspection report gives you leverage at the negotiating table and one less thing for your lender to question during underwriting. Trinity Home Inspections delivers same-day digital reports with free thermal imaging included, no upcharge, so you walk into closing with a clear picture of what you’re buying.
[
What’s included: full structural and systems review, color-coded findings, free thermal imaging, and post-inspection support to walk you through the report by phone or in person. If you’re verifying property history before you make an offer, our property, deed, and permit search service pulls records across Baldwin, Mobile, and Escambia counties. Buyers weighing negotiation leverage often pair that with our pre-listing inspection insights to understand what a seller’s own inspector may have already flagged.
Call 251-210-7376 or visit Trinityinspectionsllc to schedule your inspection and head into closing with answers instead of guesswork.
Sources
For local property record checks or negotiation guidance, OwnInAZ’s tips for buyers and borrowers covers common documentation and undisclosed debt pitfalls worth reading before you apply. Contacting a HUD-approved housing counselor directly is still the most reliable way to get answers specific to your situation.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What Disqualifies You From First-Time Home Buyer Status?
Owning a principal residence at any point in the three years before your purchase date typically disqualifies you, unless you qualify under HUD’s exceptions for single parents, displaced homemakers, or prior ownership of an uninhabitable property.
What Do You Need for a First Home Buyer Loan?
You need photo ID, two years of W-2s and tax returns, 30 to 60 days of pay stubs, two months of bank statements, and a signed gift letter if any down payment funds are gifted, per CFPB documentation guidance.
What’s the Difference Between Preapproval and Prequalification?
Prequalification is a quick, often unverified estimate based on self-reported numbers, while preapproval involves submitting documents for a lender to verify your income, credit, and assets before issuing a conditional commitment.
How Do I Compare Loan Offers From Different Lenders?
Compare the annual percentage rate, not just the interest rate, along with lender fees, discount points, and estimated closing costs across at least two or three lenders before choosing one.
Does a Home Inspection Affect Loan Approval?
Yes, especially for FHA loans, where the property must meet minimum condition standards, and a Trinity Home Inspections report can flag issues before they stall your underwriting timeline.
Recommended

